British multinational Diageo Plc has disclosed that it has booked a Sh5.57 billion charge (loss) relating to the sale of its stakes in EABL and UDV Kenya Limited to Japan’s Asahi Group Holdings, implying that it valued the businesses higher than the Sh389.3 billion sale price.
Diageo told its shareholders that the charge was recognised in its financials for the year ended June 2026 as a non-operating item, meaning it does not relate to production, marketing and distribution of products.
The company said that under its accounting standards, such non-operating charges are directly attributable to gains and losses on sale or prospective sale of businesses, brands or distribution rights.
They also relate to gains or losses that arise when an investment becomes an associate, or an associate becomes a subsidiary, and any other unusual non-recurring items deemed large enough to distort the performance of the company.
“On December 17, 2025, Diageo announced the sale of its shareholding in East African Breweries PLC and its shareholding in the Kenyan spirits business to Asahi Group Holdings, and a non-operating charge of $43 million attributable to the prospective sale was recognised in the year ended 30 June 2026,” said Diageo.
For the 65 percent stake in EABL, Diageo and Asahi agreed a consideration of $2.354 billion (Sh305.5 billion), while the sale of the British multinational’s 53.68 percent holding in spirits producer and importer UDV Kenya was priced at $646 million (Sh83.8 billion).
For the EABL segment of the transaction, the sale price was seen as a large premium on the prevailing market price of the company’s shares at the Nairobi Securities Exchange (NSE) at the time of the announcement, and its book value.
The Japanese firm however cautioned EABL minority investors, who it did not give a buyout offer, against doing a like-for-like comparison of the Diageo purchase price and the stock market value of EABL’s shares.
Asahi said that the purchase price of the 514 million EABL shares came with additional commercial arrangements with the British multinational, besides customary contractual protections.
Asahi’s valuation of the 65 percent stake was equal to Sh594 per share, well above the brewer’s current NSE trading price of Sh287 per unit, which is equivalent to a market capitalisation of Sh226.9 billion.
Both the Asahi and NSE valuations are also higher than EABL’s current book value of Sh50 billion, which equates to a net asset value (NAV) per share of Sh64 per share. The premium is derived from items such as brand valuations and distribution rights.
“The Diageo consideration does not represent, and should not be construed as, a direct price per share or valuation of the ordinary shares of EABL,” Asahi said in a public announcement when it announced the deal in December.
“Caution should therefore be exercised against forced equivalence or direct look-through in respect of the price for the ordinary shares of EABL.”
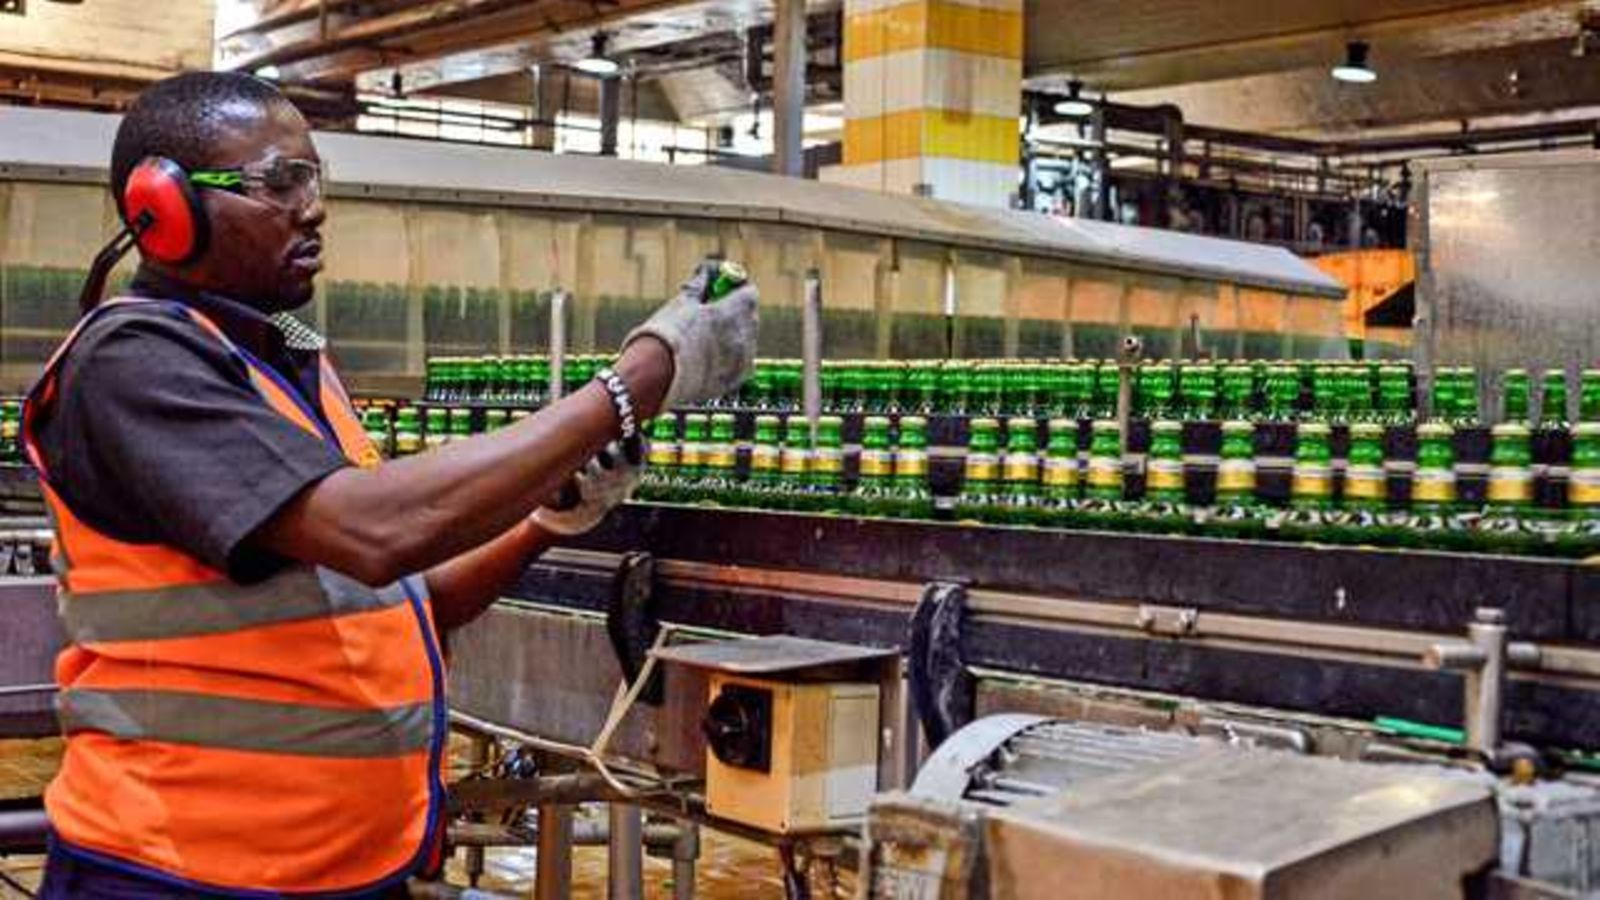
The agreement between Diageo and Asahi will for instance, see EABL continue to manufacture and distribute Diageo’s Guinness beer under long-term licensing agreements.
The UK multinational will also renew agreements with EABL to produce certain Diageo spirits such as Smirnoff and Captain Morgan, and ready-to-drink brands such as Smirnoff Ice and Origin on licence terms once the deal is concluded.
The companies did not however, disclose the monetary value of these additional contractual agreements that swelled the transaction value beyond EABL’s book value.
Diageo’s sale of its East African businesses is part of its strategy to focus on more profitable brands and regions, besides simplifying the business, including its supply chains.
The multinational has implemented divestitures in various markets in recent years, including in Nigeria, Ghana and Seychelles.
“As an executive team, we are confident that these changes will create stronger total shareholder returns and will allow us to look at the choices we make, the capital we deploy, and the returns these generate,” Diageo’s chief executive Sir Dave Lewis said.
“Over the next two years, we will invest $1.2 billion in restructuring to generate $1 billion in annual savings. We will invest this back to advance innovation, our overall competitiveness and to protect underlying profitability.”
The sale of EABL is expected to further reduce Diageo’s sales and earnings from Africa where net revenue declined to $2.52 billion in the year ended June 2026 from Sh$2.68 billion the year before.
Operating profit, before exceptional items, in the region meanwhile increased to $356 million from $283 million.
While Diageo is retreating from East Africa, Asahi is betting that expansion in the premium beer category will help boost sales growth in the future.
“Looking ahead, premiumisation is expected to accelerate across East Africa, driven by ongoing economic modernisation and urbanisation. Against this market backdrop, there is tremendous potential to expand our international premium brands, such as Asahi Super Dry and Peroni Nastro Azzurro, and by doing so, we believe we can generate crucial synergies that augment EABL’s business foundation,” Asahi said.